Economics as a social science
Economics is a social science concerned with how people and societies make choices when resources are scarce.
Its social nature means economic decisions involve people, organizations and their interactions.
The study of economics has two main perspectives: microeconomics and macroeconomics.
Microeconomics focuses on individuals, firms and industries; macroeconomics examines the economy as a whole.
Factors of production and scarcity
The four factors of production are land, labour, capital and entrepreneurship.
Land represents natural resources; labour represents human work.
Capital means produced resources used in production; entrepreneurship organizes resources and involves risk-taking.
Scarcity exists because human needs and wants exceed the limited resources available to satisfy them.
Scarcity therefore creates the problem of choice and makes resource use important for sustainability.
The basic economic questions
Scarcity means every economy must answer the basic economic questions.
What and how much to produce? Decide which goods and services should be produced and in what quantities.
How to produce? Decide how scarce factors of production should be organized and used.
For whom to produce? Decide how the resulting goods and services are distributed.
These questions may be answered through markets, government intervention, or a combination of both.
The production possibilities curve model
The production possibilities curve (PPC) shows attainable combinations of two outputs using available resources and technology.
The basic model considers two outputs with given resources and productive technology.
Points on the PPC indicate efficient use of resources; points inside indicate unemployed or underused resources.
Points outside the PPC are unattainable with current productive capacity.
Moving along the PPC illustrates scarcity, choice and opportunity cost.
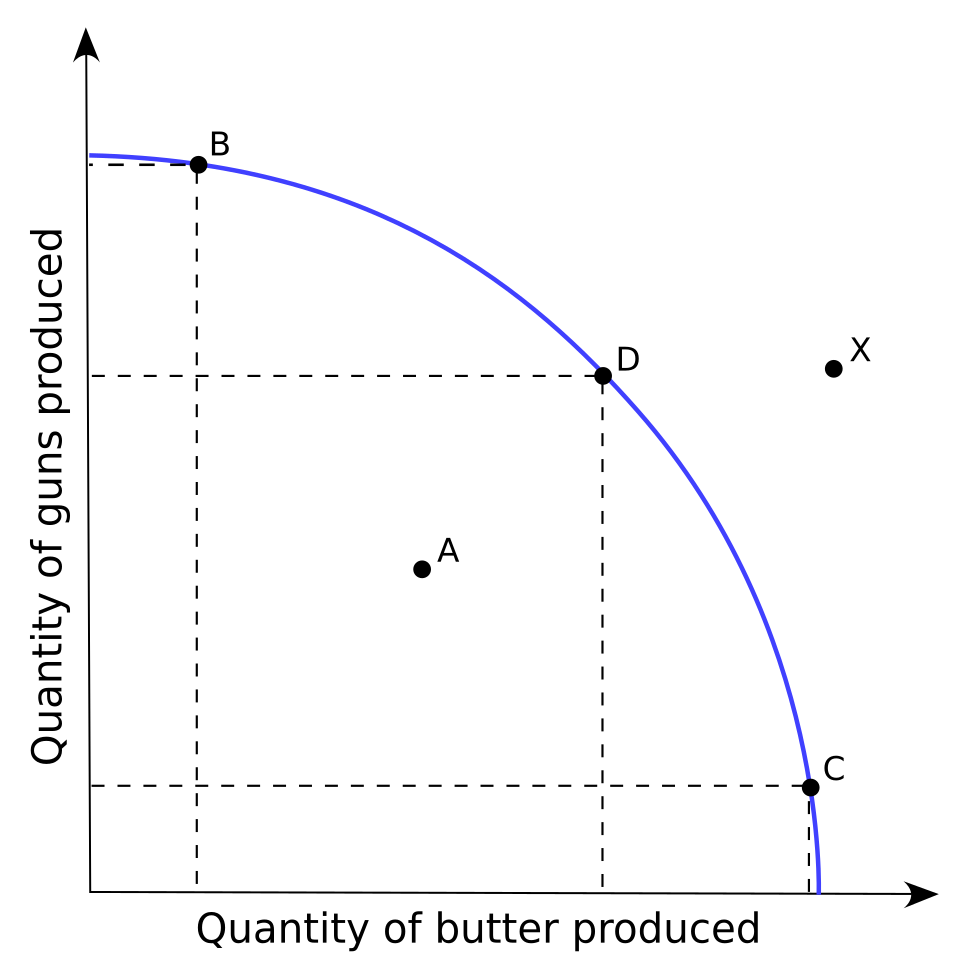
Points on the PPC represent efficient production, while a point inside shows underused resources. A point outside represents output that cannot currently be achieved with existing productive capacity. Source
Checklist: can you do this?
Can you explain why scarcity creates choice and opportunity cost?
Can you distinguish land, labour, capital and entrepreneurship?
Can you state the three basic economic questions?
Can you distinguish a free market, planned and mixed economy?
Can you interpret efficient, inefficient and unattainable points on a PPC?
Can you distinguish increasing from constant opportunity cost using PPC shapes?
Can you distinguish actual growth from growth in production possibilities on a PPC?
Can you draw a circular flow model showing the five decision-making sectors, leakages and injections?
The nine central concepts
Scarcity, choice and efficiency are central concepts.
Equity, economic well-being and sustainability are central concepts.
Change, interdependence and intervention complete the nine concepts.
These concepts provide recurring lenses for understanding economic choices and outcomes.
Use the precise IB terminology when connecting economic reasoning to these concepts.
Opportunity cost and free goods
Opportunity cost is the cost of choice: what must be forgone when one option is chosen.
In an exam, identify what is sacrificed rather than simply stating a monetary cost.
A free good is not scarce and therefore has zero opportunity cost.
A product with a zero price is not necessarily a free good if scarce resources were required to provide it.
Economic systems and decision-making
Economic system | Main means of answering economic questions | Key distinction |
|---|---|---|
Free market economy | Mainly the market | Economic decisions are largely decentralized. |
Planned economy | Mainly government planning | Major economic decisions are centralized by government. |
Mixed economy | Markets and government intervention | Combines market decision-making with government involvement. |
Opportunity cost and growth on the PPC
A bowed-out PPC represents increasing opportunity cost: producing additional units of one good requires progressively larger sacrifices of the other.
A straight-line PPC represents constant opportunity cost because the trade-off remains unchanged along the frontier.
Actual growth can be represented by movement from an inefficient point inside the PPC toward the frontier as unemployed resources are used.
Growth in production possibilities is represented by an outward shift of the PPC as productive capacity increases.
Distinguish carefully between a movement toward the PPC and a shift of the PPC in diagrams.
The circular flow of income model
The circular flow of income model represents interdependence between economic decision-makers.
The required decision-makers are households, firms, government, banks and the financial sector, and the foreign sector.
Households and firms interact through flows of resources, goods and services, and money.
Government, financial institutions and foreign households and firms extend the basic model.
For diagrams, clearly label each sector and show the direction of relevant flows.
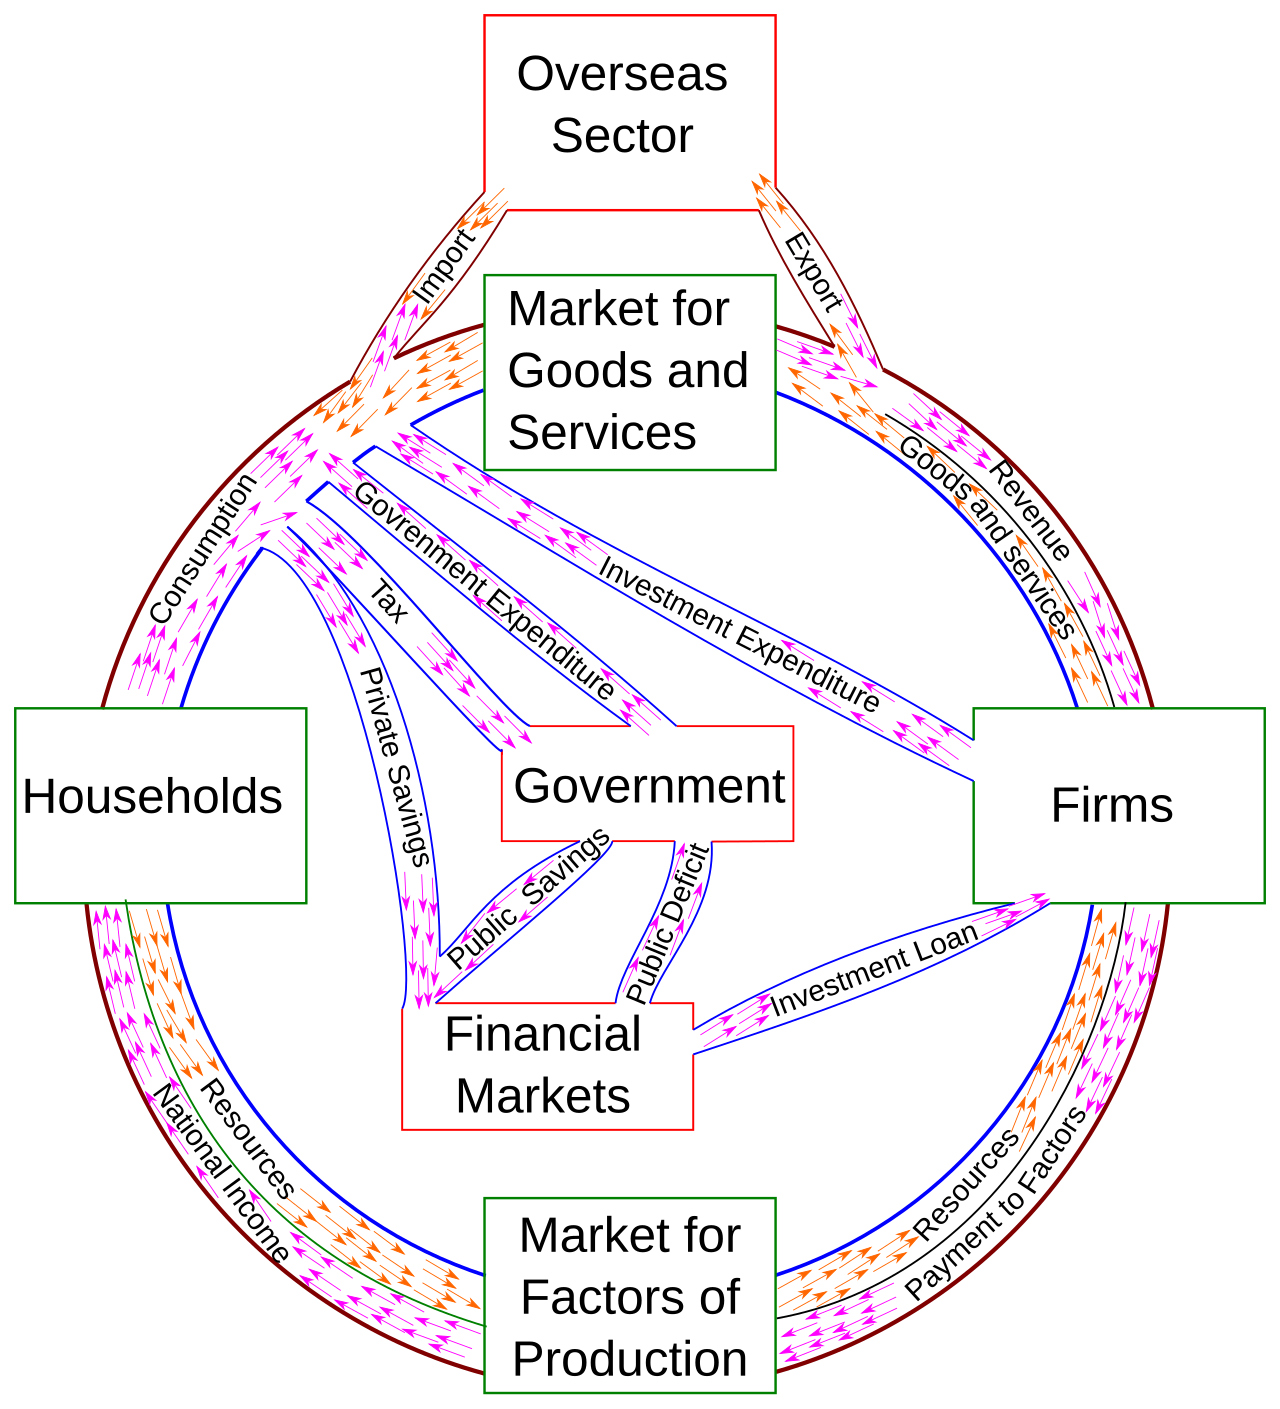
The diagram shows how households, firms, government, financial markets and the overseas sector are interdependent. Follow the arrows to distinguish flows of money from flows of resources, goods and services. Source